Tuesday, September 21, 2010

Moms Making Money

For example: Years ago, Whoopi Goldberg asked (paraphrasing), "How can you tell a black welfare mom not to accept drug money from her son?" Well, I am a black man who would tell the mom not to accept the money because selling drugs is wrong. Liberal America would consider my answer too simple, judgmental, and religious. Pandering to the mom's lower nature, liberals would say, "That's easy for you to say, Lloyd. How dare you expect a welfare mom to rise to your standard?"

Life is busy. But if you don’t have time to go to the bank, would you trust a stranger to deposit a check for you? Users of TaskRabbit, a network of part-time personal assistants, do.


The site pairs assistants, called runners, with overtasked city dwellers. TaskRabbit has more than 300 runners, who have all undergone a background check, and they accept tasks online from thousands of users in Boston and San Francisco. Task requests include running to the bank, jump starting a car and building furniture inside a stranger’s home. My request for groceries last Thursday night resulted in two runner responses within 15 minutes, and orange juice was delivered to my neighborhood within an hour.


Founded in Boston, TaskRabbit raised $1 million from Baseline Ventures and Floodgate in 2009. The startup recently raised $850,000 more from First Round Capital and existing investors.


The site expanded to the San Francisco Bay Area this summer. San Francisco is already doing as much task volume as Boston, and the company plans to expand to more cities soon, according to TaskRabbit CMO Anne Moellering. Urban, sophisticated, wired cities top the short list of next stops for the company, she said, naming Chicago, Austin and Portland as potential destinations. Though the site is not yet profitable, TaskRabbit makes money by taking a 12 to 28 percent cut of each paid task, depending on the size. For a $19 dry cleaner pickup, TaskRabbit makes $4, while the runner gets to keep $15.


Runners range in age from 18-year-old students to 70-year-old retirees. The site is popular with enterprising moms looking to defray the cost of a trip to Target. One rabbit, a student on leave from school, said he had completed seven tasks in a week and was paid as much as $60 for one job, though the average task pays $20 to $25. Moellering said the company’s top rabbits, who she called “rabid rabbits,” could make more than $20,000 in a year.


Though dedicated rabbits can make substantial earnings, the company is careful to designate runners as independent laborers, rather than employees or contractors. Runners sign no contracts, and TaskRabbit only has to report their income if it exceeds $600 per year. Runners may still be eligible for unemployment benefits as they complete tasks, and it is a runner’s responsibility to verify eligibility.


Despite safety concerns (many users invite strangers to their homes), more than 80 percent of customers return for repeat tasks. Runners don’t get paid until a user says the job is complete, and users rate runners after each task.


Initially called RunMyErrand, the site focused primarily on errands. In part due to the evolution of jobs listed on the site, the company changed its name to TaskRabbit this year. It now covers anything on a to-do list. Virtual tasks, such as making PowerPoint slides or merging contact databases, are increasing in popularity. The startup may launch group buying in the next couple months, allowing users to team up with others requesting goods from the same store, and the company is also considering a “panic button,” which would charge users a premium flat rate for immediate needs.


TaskRabbit has raised a total of $2 million in seed funding to date.


Next Story: Talk of 99-cent iTunes TV rentals points to revamped Apple TV Previous Story: CollegeOnly just misses Scoop on college student social networks


David Helfenbein: The Facebook <b>News</b> Feed and Twitter Generation

The largest misconception about Generation Y is that technology is a replacement for interpersonal dialogue. Technology is becoming more ever-present, and Gen Y is still managing to talk to one another.

More Fallout Online art dribbles out MMO <b>News</b> - Page 1 | Eurogamer.net

Read our MMO news of More Fallout Online art dribbles out.

Sony product-lineup at Photokina 2010: Digital Photography Review

Sony product-lineup at Photokina 2010: Sony has issued a press release about the new product developments it's showcasing at Photokina 2010. Highlights include a firmware update for the NEX series (covered in a separate news story), ...


robert shumake

David Helfenbein: The Facebook <b>News</b> Feed and Twitter Generation

The largest misconception about Generation Y is that technology is a replacement for interpersonal dialogue. Technology is becoming more ever-present, and Gen Y is still managing to talk to one another.

More Fallout Online art dribbles out MMO <b>News</b> - Page 1 | Eurogamer.net

Read our MMO news of More Fallout Online art dribbles out.

Sony product-lineup at Photokina 2010: Digital Photography Review

Sony product-lineup at Photokina 2010: Sony has issued a press release about the new product developments it's showcasing at Photokina 2010. Highlights include a firmware update for the NEX series (covered in a separate news story), ...


For example: Years ago, Whoopi Goldberg asked (paraphrasing), "How can you tell a black welfare mom not to accept drug money from her son?" Well, I am a black man who would tell the mom not to accept the money because selling drugs is wrong. Liberal America would consider my answer too simple, judgmental, and religious. Pandering to the mom's lower nature, liberals would say, "That's easy for you to say, Lloyd. How dare you expect a welfare mom to rise to your standard?"

Life is busy. But if you don’t have time to go to the bank, would you trust a stranger to deposit a check for you? Users of TaskRabbit, a network of part-time personal assistants, do.


The site pairs assistants, called runners, with overtasked city dwellers. TaskRabbit has more than 300 runners, who have all undergone a background check, and they accept tasks online from thousands of users in Boston and San Francisco. Task requests include running to the bank, jump starting a car and building furniture inside a stranger’s home. My request for groceries last Thursday night resulted in two runner responses within 15 minutes, and orange juice was delivered to my neighborhood within an hour.


Founded in Boston, TaskRabbit raised $1 million from Baseline Ventures and Floodgate in 2009. The startup recently raised $850,000 more from First Round Capital and existing investors.


The site expanded to the San Francisco Bay Area this summer. San Francisco is already doing as much task volume as Boston, and the company plans to expand to more cities soon, according to TaskRabbit CMO Anne Moellering. Urban, sophisticated, wired cities top the short list of next stops for the company, she said, naming Chicago, Austin and Portland as potential destinations. Though the site is not yet profitable, TaskRabbit makes money by taking a 12 to 28 percent cut of each paid task, depending on the size. For a $19 dry cleaner pickup, TaskRabbit makes $4, while the runner gets to keep $15.


Runners range in age from 18-year-old students to 70-year-old retirees. The site is popular with enterprising moms looking to defray the cost of a trip to Target. One rabbit, a student on leave from school, said he had completed seven tasks in a week and was paid as much as $60 for one job, though the average task pays $20 to $25. Moellering said the company’s top rabbits, who she called “rabid rabbits,” could make more than $20,000 in a year.


Though dedicated rabbits can make substantial earnings, the company is careful to designate runners as independent laborers, rather than employees or contractors. Runners sign no contracts, and TaskRabbit only has to report their income if it exceeds $600 per year. Runners may still be eligible for unemployment benefits as they complete tasks, and it is a runner’s responsibility to verify eligibility.


Despite safety concerns (many users invite strangers to their homes), more than 80 percent of customers return for repeat tasks. Runners don’t get paid until a user says the job is complete, and users rate runners after each task.


Initially called RunMyErrand, the site focused primarily on errands. In part due to the evolution of jobs listed on the site, the company changed its name to TaskRabbit this year. It now covers anything on a to-do list. Virtual tasks, such as making PowerPoint slides or merging contact databases, are increasing in popularity. The startup may launch group buying in the next couple months, allowing users to team up with others requesting goods from the same store, and the company is also considering a “panic button,” which would charge users a premium flat rate for immediate needs.


TaskRabbit has raised a total of $2 million in seed funding to date.


Next Story: Talk of 99-cent iTunes TV rentals points to revamped Apple TV Previous Story: CollegeOnly just misses Scoop on college student social networks


mom is happy I will now finally make money! by skier2423


robert shumake

David Helfenbein: The Facebook <b>News</b> Feed and Twitter Generation

The largest misconception about Generation Y is that technology is a replacement for interpersonal dialogue. Technology is becoming more ever-present, and Gen Y is still managing to talk to one another.

More Fallout Online art dribbles out MMO <b>News</b> - Page 1 | Eurogamer.net

Read our MMO news of More Fallout Online art dribbles out.

Sony product-lineup at Photokina 2010: Digital Photography Review

Sony product-lineup at Photokina 2010: Sony has issued a press release about the new product developments it's showcasing at Photokina 2010. Highlights include a firmware update for the NEX series (covered in a separate news story), ...




Saturday, September 18, 2010

how to budget personal finances


I am a 25 year old college student (school, job + savings, back to school… long story) and boy do I wish I knew about all the resources available to me back then. Good for you for starting early!


Lucky for me I have 1 parent (divorced) who is so bad with money that I have been scared into financial responsibility from a young age. Was I perfect? Hahaha.. but I am doing better than 95% of my friends are right now so I guess I am doing something right?


Here is my advice:


1. GET A JOB! - 2 shifts a week is all it takes. I have friends who just graduated from college without ever having a job. Result? No work experience so nowhere will hire them. Some had problems even getting an internship! Try for customer service jobs. Employers value people skills more than flipping burgers.


2. BUDGET! - Cant teach an old dog new tricks so it is best to start young. Add up your monthly expenses such as rent/insurance/cell/gas/etc and divide by 2 or 4 (depending on weekly/bi-weekly payday). Put this money in savings and no touchy! Once you can live on that budget a certain % for an emergency fund and then % for savings. The rest is your “fun” money. As others have said: pizza, ipods, and clothes are “fun money” and NOT emergencies!


3. DEBIT, CREDIT, or CASH?


DEBIT- I am a die hard debit card user. My credit union has detailed (free) online banking. I check my online bank statement in the morning and at night and go over my spending. Think of it as an instant virtual slap in the face about your spending habits. It hurts for the best.


CASH - Some people just cant be responsible enough to respect the plastic and do better with cash. Try and keep bigger bills on you. Breaking a $5 is less mentally painful than breaking a $20. $1s are dangerous. That can of coke is “only $1″. $7 a week, $30 a month. It adds up.


CREDIT - Many say don’t get a credit card, but I disagree. If you are responsible college is a great time to build credit (unless you have some serious control issues… if that is the case, these are not the droids you are looking for…). Not building credit early is the BIGGEST regret I have. Good credit means better rates when buying a house or a car. Do your research first. Consider a student, or if you have to a secured card.


More about credit-


*Do NOT apply for a credit card on campus. It is like selling your soul for a candy bar. Every time you apply for a credit card they run a credit check, which “pings” you. Too many pings hurts your credit score. Not good. Friend did that at every kiosk that offered something free to sign up when she was 20. This was 7 years ago and her credit is still recovering! The same is true for store credit cards. Do.Not.WANT!

*Pick a required expense, such as gas or cell phone bill and put it on the credit card. Pay off the card at the end of each month. Repeat.

*Do NOT use your credit card to buy “fun money” purchases. No clothes, no ipods, no pizza. This is why you have your debit card of cash. Don’t even think about it mr.!


4. EATING/DRINKING - This is going to be the weird random one from one young person to another.(Part of this only applies to you on/after your 21st birthday!) The young person’s life revolves around being social. For a 20 something this normally involves dinner and/or drinks with friends. It is expensive! So much money can be saved if you plan ahead!


*Eating - Going out to eat is a much needed social experience but NEVER go out to eat starving! Just like you don’t go shopping when you are hungry you never want to experience the whole “eyes bigger than stomach” thing while dining out. Have a snack an hour or so before you meet friends for dinner. This will help you avoid ordering that $8 appetizer! Also, try and order things that reheat or are good cold. LEFTOVERS! Also, water is free. It is good for you! Coke is $3. Go buy yourself a 12 pack and have one when you get home.


*Drinking - Most 20 somethings drink. It is a very expensive part of our lives. It is a social event to help us forget about school and work. We like bars. Unfortunately $5 for a beer is highway robbery! NEVER go to a bar completely sober (when you are 21+ & no drinky + drivey!). Have a drink or 2 at home and then have a beer at the bar. You will save TONS. Also, bring cash to a bar. Only bring as much cash as your sober self would like to spend. Alcohol impairs judgment. Sober you will thank drunk you for not spending. Drunk you will thank sober you for being smart enough to make sure you can afford the advil to take care of that hangover the next day. It is a win win.


Put all that saved food and drink money towards something that will last.


5. BOOKS - Buy used whenever possible. Check online first because campus stores are normally a ripoff. Try and sell the books back online, even if they have released a new edition. Most student book stores on campus will only give you 1/2 of what someone online will be willing to give you!


6. CARS - Buy used and reliable, but not “cheap”. New cars lose tons of value when you drive them off the lot. Don’t buy a “cheap” used car on it’s last leg. Think Goldilocks - not too new, not too old, juuusssttt right! Save up as much money as possible. Pay for it in cash if you can. If not, save up at least 2/3 before purchasing and do your homework!


And whatever you do: AVOID parking tickets, speeding tickets, registration fines.. may as well light the money on fire! Or if you do not want it I will give it a nice home and save you the trouble.


Events of the last week have made the Deficit Commission an embarrassment. Co-Chair Alan Simpson is a one-man disaster movie, compulsively offending one key voting bloc after another. Commission member Paul Ryan faced an angry crowd over his anti-Social Security stance, while another Commissioner locked experienced workers out of a nuclear facility rather than provide retirement benefits.


That's right: He's cutting retirement benefits.


But if the political blowback is obvious, here's what isn't: The Commissioners who are determined to cut your Social Security benefits are going to enjoy their own retirements in comfort. Their own pension plans insulate them from the fears that many other Americans face, and they don't have the professional expertise that would help them understand those concerns. In fact, the Commission's only expert on retirement is Rep. Jan Schakowsky, and she apparently opposes benefit cuts. The rest of the Commission is dominated by people who've expressed their desire to cut Social Security, despite their own secure futures. Millions of working Americans who have contributed to Social Security all their lives will lose out if these Commissioners have their way.


Happy Labor Day.


Normally I consider it off-limits to discuss people's personal finances when discussing their political opinions. But these Commissioners' lack of subject matter expertise, along with their lack of empathy, is important. If you don't know much about the topic and are protected from the problem, what makes you credible? Their pre-established prejudices makes the situation even worse, and their own situations underscore the irony of their self-professed willingness to make "brave choices" - choices whose consequences will mean little or nothing to them.


The Commission's Social Security obsession is odd anyway, since the projected Social Security shortfall comes out to only 0.7% of GDP. Nevertheless, these Commissioners have made their benefit-cutting intentions plain, presumably because they want to offer up America's seniors as a sacrifice to the bond markets. So how will these would-be income-slashers for the elderly make out in their own golden years? They'll be golden.


Consider Commissioner Alice Rivlin. Rivlin co-authored a paper that called for raising the retirement age and other benefit cuts, and recently released a specious paper about "Saving Social Security." As a former HEW Undersecretary, CBO Director, White House Budget Director, and Federal Reserve Vice Chair, she will presumably enjoy a comfortable retirement supported by multiple public pensions. Says Rivlin: ""We can't get out of this problem without doing both spending cuts, especially slowing the growth of entitlement, and tax increases."


Experts on Social Security finance (including the long-time Chief Actuary for the program) flatly disagree with Rivlin, pointing out that an adjustment to the payroll tax cap would unquestionably be enough to get the job done. They have the numbers to prove it. So why does Rivlin, who does not have their expertise in this area, disagree? Go ask Alice.


Co-Chair Erskine Bowles brokered a deal with Newt Gingrich to cut Social Security in the 1990s, when he served as Bill Clinton's Chief of Staff. Before that he headed the Small Business Administration, so his government tenure presumably qualifies him for a Federal pension. If not, don't worry: He receives $425,000 per year in his current job running the public universities of North Carolina, and the people of North Carolina are presumably also funding a pension on his behalf. To his credit, Bowles pledged to donate $125,000 of his salary for need-based student funds - but then, he can afford it. As the son of a US Congressman, Bowles had the education and connections needed to make millions as an investment banker. The added income he earns today as a Board member for General Motors and Morgan Stanley will help, too - and his government experience undoubtedly helped him win those positions, too.


Republican Rep. Paul Ryan, an aggressive advocate of Social Security cuts and privatization, will also enjoy his sunset years in comfort, thanks to a publicly-funded pension from his tenure as a Congressman. (He'll presumably earn even more as a result of his employment as an aide to two United States Senators.) Rep. Jeb Hensaerling has served as both a Representative and as an aide to Sen. Phil Gramm, so he should be safe from financial insecurity in his old age too .


The average annual pension payments for former members of Congress ranged from $41,000 to $55,000 in 2002, considerably more than the average $13,836 that Social Security recipients received in 2009. Yet neither Ryan nor Hensaerling have proposed cutting Congressional retirement benefits - nor should they. Sound pension plans like theirs were once available to most working Americans, and more effort should be made to restore them.


Former SEIU President Andrew Stern, who once might have been counted on to defend Social Security, recently sneered at Commission critics as "assassins of change" while saying that "all entitlements should be on the table." Mr. Stern's annual pension is $152,000 - and he retired at the age of 59, not 70. Nevertheless, Stern now publicly muses about "whether defined benefit pensions can really exist in the long run in a globalized economy."


Judd Gregg, who wants to raise the retirement age to 70, will receive a Federal pension for his Senate position. Gregg, like Alan Simpson, is the son of a Governor (self-made men, you might say), which means that public pensions also ensured that neither of them had to worry about supporting their aged parents. Tom Coburn, another would-be Social Security cutter, will receive a Congressional and Senatorial pension too.


David Cote, the CEO of Honeywell, provides some "private enterprise" perspective to the Commission's work. But Cote's wealth comes in part from Honeywell's government contracts, which exceed $4 billion annually. What's more, Cote's "free enterprise" ethic didn't stop him from making sure that Honeywell grabbed a few million in stimulus money from the taxpayers, too. A few billion from the Pentagon here, a few million more from Uncle Sam there - that'll plump up the nest egg a little for Mr. Cote's sunset years.


Cote made the headlines this week when Honeywell locked out the union workers at a nuclear power plant over a labor dispute - even though the workers agreed to stay on the job to protect public safety. Instead, Cote hired replacements and put them through a pared-down training process. The image of Homer Simpson comes to mind, pushing the wrong buttons and spilling beer on the reactor console - which would presumably make Cote Mr. Burns.


But it's no joking matter. Apparently there's real danger, which is why the Nuclear Regulatory Commission reportedly stepped in to block Honeywell from distilling uranium with its crew of replacement workers And what are the union and Honeywell arguing about? Honeywell's raising health care costs - and eliminating retiree pension plans for new workers.


That's right. A member of the Commission that's pretending to judge our retirement security with impartiality would rather have hastily-trained amateurs handle nuclear materials than bargain openly with his workers - about their retirement. D'oh!


As for Simpson (Alan, not Bart), to say that he suffers from "political Tourette's syndrome" would be a disservice to Tourette's sufferers. Most of them don't really say socially objectionable things, and those who do (it's called "coprolalia") don't mean what they say. But Simpson does. By attacking senior citizens as "greedy geezers," then offending women with his "milk cow with 100 million tits" comment, and now offending veterans' groups, Simpson has now hit the voting bloc trifecta.


And Cote's outraged labor, a fourth group. But the problem isn't Simpson anymore, or Cote for that matter. It's the Commission itself. The coprolalic curmudgeon Simpson has done a service to the nation. He's drawn attention to the Commission, and to the anti-Social Security biases held by so many of its members - all of whom will retire in comfort, thanks to those whose benefits they would cut. It's the comfortable afflicting the afflicted.


If these Deficit Commission members want their recommendations to have any credibility, they should pledge to live on the same Social Security benefits that they would impose for other Americans. Better yet, they should dedicate themselves to helping provide every American with the kind of retirement security they enjoy. That was part of the social contract this nation embraced during its years of greatest economic growth, the fulfillment of a promise that a lifetime of work should never end with years of deprivation. They should be working to restore that contract, not erode it even further.


One thing is clear: This Commission has no business making recommendations about Social Security.


(Sign a petition asking Congress and the President to protect Social Security from the Deficit Commission. Roger Hickey has more here.)


Additional links:


* Sam Seder and I discussed Social Security this week while co-hosting The Young Turks.


* For further reference on the Commission's members and their biases, see Firedoglake and Talking Points Memo.


* House Democrats are vowing to protect Social Security from any cuts. The polls show why that's a very wise idea.


eric seiger dermatology how to lose weight fast penis extender

Baltimore Crime: Saturday crime <b>news</b>

Saturday crime news. State Senator Ulysses Currie pleaded not guilty to federal corruption charges. Triple stabbing on an MTA bus in West Baltimore. posted by ppatin at 11:07 AM ...

The Hockey <b>News</b>: Edward Fraser&#39;s blog: THN.com Blog: Flyers “way <b>...</b>

Philadelphia's senior vice president explains why this year's team will be even tougher and why their goaltending situation is where they want it to be.

<b>News</b> Roundup: Kaley Cuoco Will Miss Multiple &#39;Big Bang Theory <b>...</b>

'The Big Bang Theory' star Kaley Cuoco will sit out more than the previously reported one episode due to her broken leg. According to The Ausiello.


Using Freeware To Increase Your Effectiveness At Work by Free Software Directory


Tuesday, September 14, 2010

personal finances help


Well, it's nice of Jim Geraghty at Rich Lowry's NRO to try and tell us what a wonderful, somewhat conservative Republican Mike Castle is. Think about it, folks. In the video Jim posts, one I also posted, Castle basically claims we are now in the era of bi-partisan national health care, whether we like it, or not. And that doesn't bother NRO, they actually think it's a good thing.


It's time to admit what a dismal failure Rich Lowry is. It isn't as if it's a big secret in conservative circles. National health care? Obviously, that's no problem, according to Lowry's NRO. The truth is, NRO isn't capable of leading anything when it comes to a movement, not a conservative one, any way. I don't even want  to think of the kind of movement a conservative should associate with Lowry's NRO today.


As for what they don't want you to know about Mike Castle, how's this from Redstate, for starters, with more below. Castle has forty years in, allegedly, as a public servant. How many honest people who work hard for a living every day are able to accumulate personal wealth in excess of 8 million dollars on what is little more than an honest pay check? Why isn't NRO interested in whatever corruption could lead to Castle accumulating that kind of wealth as a member of the House?


He is a forty year career politician who happens to call himself a Republican, as once did Charlie Crist, Arlen Specter and Jim Jeffords. Mr. Castle is a habitual tax raiser. He is unwaveringly pro abortion and he has earned an F- rating from The NRA. He voted for TARP, Porkulus, the auto and banking industry takeovers, Cash for Clunkers as well as Cap and Trade. Most recently, he co-sponsored the disclose act which is nothing more than an assault on the first amendment designed to muzzle his political opposition.


While on the topic of opposition; Mr. Castle has made it clear that were he elected senator, regardless of his political affiliation, he has no intention of opposing current Democrat policies. This is entirely consistent with Mike Castle’s long liberal record of growing government.


In his forty years as a “public servant” Mike Castle has managed to accumulate for himself an estimated $8 million dollar personal net worth. Now he has decided to make an issue of his conservative primary challenger’s finances.


NRO doesn't, as Buckley intoned, stand athwart history and yell stop, any more. They stand outside corporate and donor offices saying, how much? That, when they're not standing outside establishment Republican's Hill offices saying, can I please come in? Look how nice we were, endorsing John McCain! Look at how we embarrassed ourselves to help elect your pick, liberal Mike Castle in Delaware.


We're NRO. We're the conservative voice of American politics (wink wink). Okay, really, we're just Republican whores and we have absolutely no shame about it. Just keep the cash and the access coming, we'll be good little boys and girls.


As if John McCain wasn't enough and perhaps arguably excusable - now it's liberal Mike Castle, too? They're smart enough to know Castle plays the usual games with his voting, providing just enough cover to remain a Republican, while selling us out on everything that truly counts. An F rating from the NRA. He voted for the Disclose Act, Cap and Trade, S-CHIP, against the surge. He's fully in bed with the SEIU. Read it at link.


And that's who Buckley's NRO is schilling for today? What a disgrace as an allegedly conservative magazine. Bill Buckley wouldn't line his bird cage with the establishment rag Lowry has made NRO into today. While we're throwing out corrupt politicians, we might do well to throw out Lowry and some of the GOP flacks and hack writers at NRO so willing and quick to sell out conservatism today, as well.


Solopreneurs often feel that they don't need a business plan, especially if they're not looking for financing.  Is this true? When do you need a plan? How complex does it have to be?


To help unravel the solo business plan mystery and the "how to" of it all, I turned to small business consultant, Doug Dolan. Here's what Doug has to say:


One of the top five questions I get from solopreneurs is, “Do I need a business plan?” My answer is always, yes. However, this doesn’t mean you need a formal plan. The detail, complexity and length of your plan will vary depending on these key factors:


1. The complexity of your business
2. The amount and source of your funding
3. The severity of the damages you will incur if your business fails


Business plans run the spectrum from a one-page outline or mini-plan to a 30-page formal business plan.


For example, if you wish to start an internet-based business using a meager portion of your savings to bring in some secondary, passive income through affiliate sales while working your day job, you can get started right away with a basic outline or mini-plan.


However, if you are passionate about designing a patentable, reverse osmosis water filtration system requiring a $500,000 investment (a combination of mortgaging your house, cashing out the kids’ college funds, and outside investment), a formal plan is necessary.


What is a mini-plan?
A mini-plan will range in size from one to 10 pages (whereas a formal plan may often span from 18 – 30 pages). So what’s in a mini-plan? At minimum, you need to have the following:


• Your UVP
• A definition of your prime prospect
• A list of your prime competitors
• The products / services you will offer
• Finances needed to reach profitability
• How you will utilize those funds
• Legal structure and other necessary licenses, permits and certifications
• A marketing plan (from ads, to social media, joint venture partners, etc….)
• Goals


What is a formal business plan?
If you do a search online for a “business plan template”, you will find a few different versions. So which do you use? Here are the sections an investor will want to see:


• Executive Summary
• Company Analysis
• Industry Analysis
• Customer Analysis
• Competitive Analysis
• Marketing Plan
• Operations Plan
• Management Bio(s)
• Financial Plans
• Appendix


What if you find yourself stuck (or simply fed-up with the process), where can you get help? You have a couple of options:


1. Do a search online for “free business plan templates”.
2. Buy a software package and fill out a template.
3. Seek out a SCORE or SBDC counselor to give you some free advice.
4. Hire a consultant (like me) to help you develop your plan and / or review and edit a final draft.
5. Hire a consultant or company to draft your plan from scratch.


Here are pluses and minuses with each of these scenarios.


Templates and software packages are simply tools. They don’t fill it out for you. Moreover, most of these options focus solely on the formal plan structure.


Seeking out a SCORE or SBDC counselor offers you a no-cost alternative, however, they will typically only help with reviewing a final plan … and often only a formal plan.


Hiring a consultant for a coaching or a review will cost you some of your start-up funds, however, you will receive more active, personal attention.


As for hiring a consultant to create a business plan for you, typically, this will cost you the most. While this will free up your time for other start-up activities, you will miss an excellent opportunity to get to know your business and your market. It is through market research and developing your plan where you gain the most insight. If you need to pitch investors, you had better know your plan forwards and backwards.


When creating a plan, let me stress a couple of key points.


1. Create a plan.
Don’t get started without a plan. It is your roadmap taking you from an idea to success. How long do you want that road to be? If you set up shop and start without a plan, chances are high, you will have to pull over along the way and ask for directions. Getting lost and asking for directions after the fact will cost you time and money.


2. If it doesn’t add up, take two steps back.
While doing additional research to complete your plan, you may find data that suggests your idea won’t make money. Don’t dismiss the negative information and only look for data that supports your idea. It is better at this point to go back to review and alter your idea and target market choice. Don’t try to sell yourself on a bad idea.


3. Have a pro review it.
If this is your first time creating a plan or if you are creating a plan for a business in an industry other than that of your previous work experience, let a successful entrepreneur review it. If you are creating a mini-plan, you may be able to start without having someone else reviewing it (although it wouldn’t hurt to let one successful entrepreneur take a quick look).


If you are creating a formal plan, you may want to consider passing it out to three pros. At least one of the three should be a successful professional with experience within your target industry while at least one should be an outsider.


Why?


First, with three pros, if there is a trend in their responses, you are less likely to dismiss what they have to say. Additionally, you will typically find that they each may give advice not provided by the other two.


Second, an industry insider will help you with the areas of your business you don’t know you don’t know while an outsider can tell you whether your plan is in plain enough English. Not everyone that you pitch your plan to will be from your target industry. You don’t want to miss out on securing money because your language confuses them.


If you have questions or find you are struggling with areas of your plan, leave a comment below or write me at doug@smallbizbreak.com.


Doug Dolan is a partner at Small Biz Break. Small Biz Break helps entrepreneurs expedite their new small business ideas to market and activates a buzz for their brand with multimedia services. Go to Small Biz Break to access their free business templates, forms and ebooks and to get more information about their small business startup and multimedia services.


penis extender

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.

Olympus E-5 professional DSLR announced and previewed: Digital <b>...</b>

Olympus E-5 professional DSLR announced and previewed: Olympus has announced the E-5 professional DSLR, replacing the E-3. Almost three years after launching its predecessor, the company has refreshed its professional flagship to ...

Samsung NX100 mirrorless compact launched and previewed: Digital <b>...</b>

Samsung NX100 mirrorless compact launched and previewed: Samsung has announced the addition of the NX100 to its NX series of mirrorless interchangeable lens cameras. It features the same 14.6Mp sensor and 3.0" OLED screen as the NX10, ...


9 Steps to Financial Freedom by kateraidt


internet marketing course

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.

Olympus E-5 professional DSLR announced and previewed: Digital <b>...</b>

Olympus E-5 professional DSLR announced and previewed: Olympus has announced the E-5 professional DSLR, replacing the E-3. Almost three years after launching its predecessor, the company has refreshed its professional flagship to ...

Samsung NX100 mirrorless compact launched and previewed: Digital <b>...</b>

Samsung NX100 mirrorless compact launched and previewed: Samsung has announced the addition of the NX100 to its NX series of mirrorless interchangeable lens cameras. It features the same 14.6Mp sensor and 3.0" OLED screen as the NX10, ...


big white booty

9 Steps to Financial Freedom by kateraidt


personal finance


BillFloat Pays Your Bills When You Can't


If money's tight and you need a little extra time to cover a bill, service BillFloat can take care of it for you and you can pay them back later.

After entering the company you need to pay, you give BillFloat the amount of the bill and your account number. It'll let you know how many days it'll float the bill (a maximum of 30) and how much you'll owe BillFloat—which is generally $5, but decreases with the number of bills you pay. BillFloat will collect a little more information about you, like how you're going to pay them back, and then you'll be all set. Just make sure you'll have the money in a month, since BillFloat won't float its own bills.


  • Average gas prices--September 13, 2010


  • You voted: letter grades edge ahead in fuel economy poll


  • For rent: 4.5 billion-year-old ball of fire


  • What Obama's transportation proposals mean for travelers


  • TomTom provides update for XL 350, XXL 550, and XL 335 GPS devices


  • Cash for appliances: Rebates aplenty in states big and small


  • Apple curtails its free case program for the iPhone 4


  • Daily Dispatch: Death of the RSS reader?; Toronto produces entertaining video to promote e-waste recycling


  • September could be Home Star’s month—or not


  • LG's 60PX950, the first THX 3D plasma, headed to the CR Test labs!


penis extender

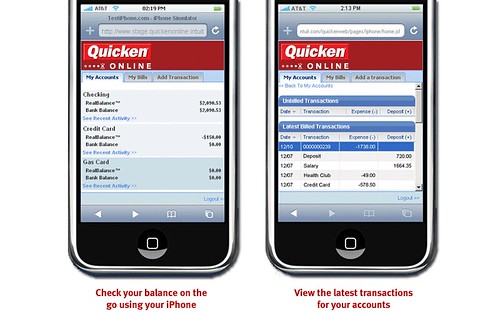
Quicken Online - Check in from your iPhone by Quicken Online


BillFloat Pays Your Bills When You Can't


If money's tight and you need a little extra time to cover a bill, service BillFloat can take care of it for you and you can pay them back later.

After entering the company you need to pay, you give BillFloat the amount of the bill and your account number. It'll let you know how many days it'll float the bill (a maximum of 30) and how much you'll owe BillFloat—which is generally $5, but decreases with the number of bills you pay. BillFloat will collect a little more information about you, like how you're going to pay them back, and then you'll be all set. Just make sure you'll have the money in a month, since BillFloat won't float its own bills.


  • Average gas prices--September 13, 2010


  • You voted: letter grades edge ahead in fuel economy poll


  • For rent: 4.5 billion-year-old ball of fire


  • What Obama's transportation proposals mean for travelers


  • TomTom provides update for XL 350, XXL 550, and XL 335 GPS devices


  • Cash for appliances: Rebates aplenty in states big and small


  • Apple curtails its free case program for the iPhone 4


  • Daily Dispatch: Death of the RSS reader?; Toronto produces entertaining video to promote e-waste recycling


  • September could be Home Star’s month—or not


  • LG's 60PX950, the first THX 3D plasma, headed to the CR Test labs!


online stock trading online stock trading how to lose weight fast

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.

Arrowheadlines: Chiefs <b>News</b> 9/14 - Arrowhead Pride

Welcome to first place. Perfect performance (offensive play calling, pass rush)? No. Feels pretty darn good? Oh, yeah. Am I the only one that thinks we'll never see Dex/Arenas getting kicked to again? As you can imagine, there are a lot ...

Denver Broncos <b>News</b> - Horse Tracks - 9/14/10 - Mile High Report

Your Daily Cup Of Orange And Blue Coffee... Horse Tracks!


Quicken Online - Check in from your iPhone by Quicken Online


big white booty